

The Bunker Outlook was contributed by Marine Bunker Exchange (MABUX)
The global bunker market is expected to remain volatile in September
The global bunker market in August was shaped primarily by Middle East geopolitical developments, crude oil volatility, tight distillate and low-sulphur fuel supply, and regional imbalances in bunker availability. The key market drivers included:
• Middle East conflict and Strait of Hormuz: Hormuz restrictions remained the main source of market volatility. Reduced Gulf exports supported prices, while signs of diplomatic progress and potential reopening of the Strait eased the geopolitical premium.
• Crude oil and geopolitical risk: Brent remained the key directional benchmark, with price movements largely driven by changing geopolitical risk perceptions.
• Global distillate tightness: Lower Middle East exports, refinery disruptions, constrained refinery output and low inventories kept diesel/gasoil supply tight and supported MGO LS prices.
• VLSFO feedstock tightness: Limited availability of low-sulphur blending components and competition with the distillate pool kept VLSFO relatively firm against Brent and HSFO.
• Regional supply imbalances: Prompt bunker availability remained tight in Singapore, Fujairah, ARA and parts of the Mediterranean, supporting regional premiums and widening the disconnect between crude and physical bunker prices.
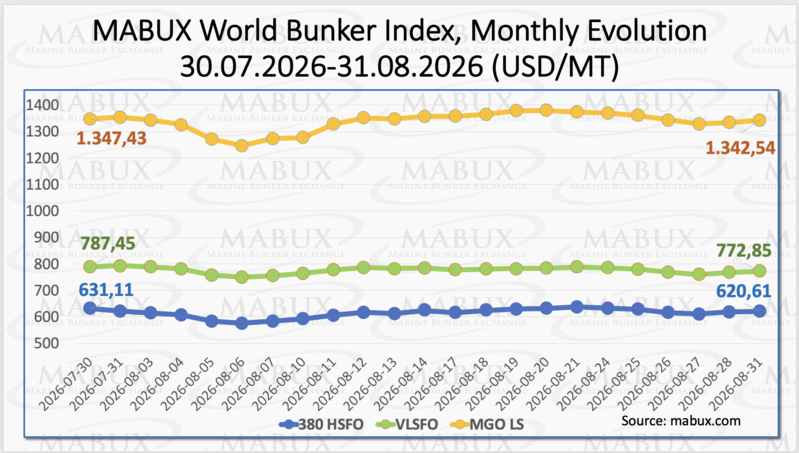
In August, the global bunker market remained relatively stable overall, despite persistently high volatility driven by the conflict in the Persian Gulf. By the end of the month, the 380 HSFO index had declined by USD 10.50, from USD 631.11/MT at the end of July to USD 620.61/MT. The VLSFO index decreased by USD 14.60, from USD 787.45/MT to USD 772.85/MT, while the MGO LS index fell by USD 4.89, from USD 1,347.19/MT at the end of July to USD 1,342.54/MT. The absence of significant price swings for most of the month was largely supported by the continued observance of the ceasefire agreement between the United States and Iran, despite sporadic violations. However, at the time of writing, a renewed escalation of tensions in the Middle East had triggered a sharp upward correction in bunker prices, increasing volatility and adding renewed upside risks to the market.
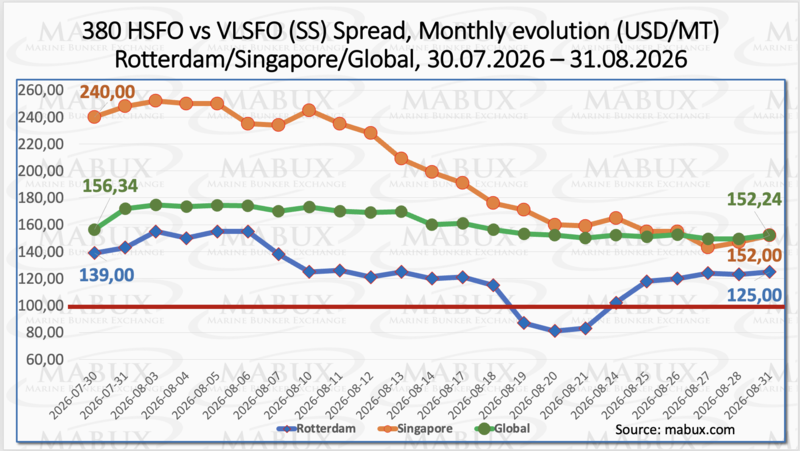
The MABUX Global Scrubber Spread (SS) – the price differential between 380 HSFO and VLSFO – narrowed by $4.10 in August, from $156.34 at the end of July to $152.24. The monthly average also declined by $14.08. In Rotterdam, the SS Spread decreased by $14.00, from $139.00 at the end of July to $125.00, briefly falling below the $100.00 mark to a monthly low of $80.00. The port’s monthly average declined by $10.50. Singapore recorded the most significant contraction, with the 380 HSFO/VLSFO spread narrowing by $88.00, from $240.00 at the end of July to $152.00, while its monthly average decreased by $17.46. Despite the downward correction, global and regional SS Spread values generally remained above the $100.00 breakeven level, continuing to support the economic attractiveness of 380 HSFO for scrubber-equipped vessels compared with conventional VLSFO. At the same time, the retreat from previous highs suggests a gradual normalization of the spread and market adaptation to the current geopolitical environment. Looking ahead, the SS Spread dynamics in September are expected to remain largely driven by developments in the Persian Gulf conflict and the prospects for its resolution. Detailed information is available in the “Differentials” section of mabux.com.
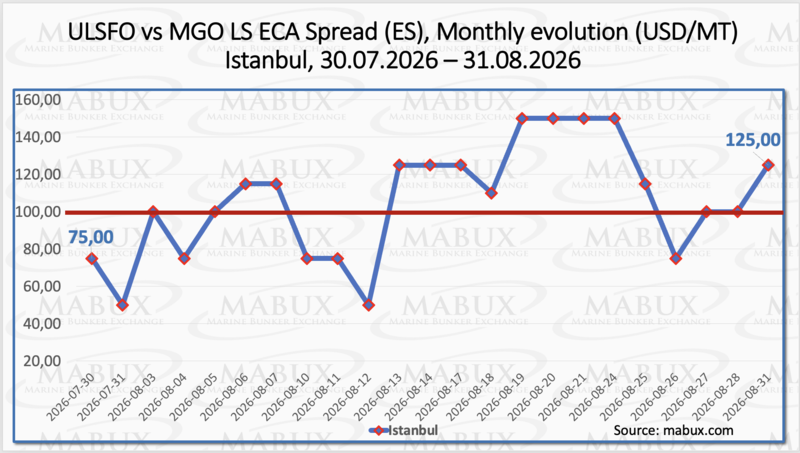
In August, the ECA Spread (ES) – the price differential between ULSFO and MGO LS – in Istanbul showed sharp multidirectional fluctuations within a range of $50.00–$150.00. By the end of the month, the index had increased by $50.00, from $75.00 at the end of July to $125.00, while its monthly average rose by $36.25. The Venice ECA Spread was not calculated due to the lack of regular quotations. Amid persistently high market volatility, the ECA Spread continued to show no sustainable directional trend, although the index moved above the psychological $100.00 mark by the end of August. Looking ahead, we expect the ECA Spread to remain subject to irregular and multidirectional fluctuations in September. Detailed information is available in the “Differentials” section of mabux.com.
Tightening global oil and gas supply is increasing the risk of a challenging winter for Europe, given the region’s continued high dependence on imported energy. EU gas storage levels currently stand well below historical norms for this time of year. If LNG imports remain at the current subdued pace, storage levels could reach only around 75% by November, when the heating season officially begins. This would fall significantly short of the EU’s 90% storage target introduced in 2022. Against the backdrop of persistent supply constraints and slower inventory rebuilding, EU authorities have recently signaled greater flexibility on storage requirements, including a potential easing of the November target. Overall, the current storage trajectory leaves the European gas market more exposed to supply disruptions and demand spikes during the upcoming winter season.
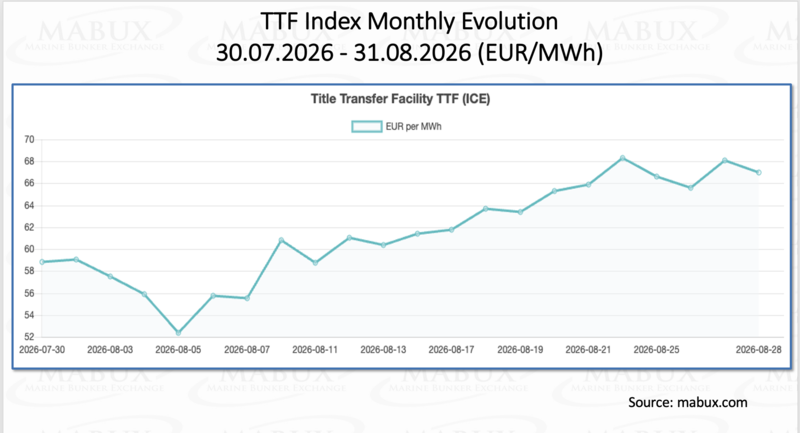
European underground gas storage levels continued to rise moderately in August. As of August 31, storage facilities were 64.73% full, up 8.34 percentage points from 56.39% at the end of July. For the first time this year, inventories moved above the level recorded at the beginning of 2026 (61.46%), exceeding it by 3.27 percentage points. At the same time, the European gas market strengthened considerably during the month. The TTF benchmark increased by €8.161/MWh, from €58.818/MWh in July to €66.979/MWh in August, indicating continued price pressure despite improving regional storage levels.
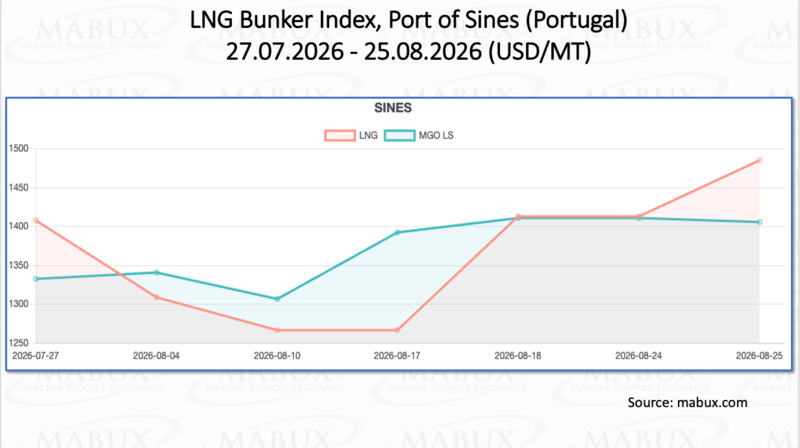
The price of LNG as a bunker fuel at the port of Sines (Portugal) continued its upward trend in August, increasing by USD 78/MT to USD 1,485/MT, compared with USD 1,407/MT at the end of July. The price differential between LNG and conventional bunker fuel remained in favor of conventional fuel, widening slightly to USD 80/MT from USD 75/MT in July. At the end of August, MGO LS was quoted at USD 1,405/MT in Sines. More detailed information is available in the “LNG Bunkering” section of mabux.com.
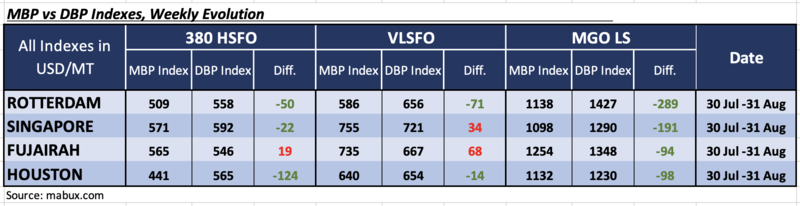
At the end of August, the MABUX Market Differential Index (MDI) – which tracks the correlation between Market Bunker Prices (MBP) and the MABUX Digital Bunker Benchmark (DBP) – showed the following trends across the world’s four major bunkering hubs: Rotterdam, Singapore, Fujairah, and Houston.
In the 380 HSFO segment, Fujairah returned to the overvalued zone, becoming the only overvalued port in this fuel category, with its premium increasing by 26 points. Rotterdam, Singapore, and Houston remained undervalued. Average monthly underpricing narrowed by 26 points in Rotterdam and 55 points in Singapore, while widening by 50 points in Houston. Houston’s MDI once again exceeded the $100 mark.
In the VLSFO segment, Singapore and Fujairah remained in the overvalued zone. Singapore’s premium increased by 26 points, while Fujairah’s declined by 26 points. Rotterdam and Houston stayed undervalued. Average monthly underpricing widened by 59 points in Rotterdam but narrowed by 2 points in Houston. Singapore’s MDI moved closer to the 100% MBP/DBP correlation level.
In the MGO LS segment, all four ports remained undervalued. Average monthly underpricing widened by 136 points in Rotterdam, 26 points in Singapore, and 79 points in Fujairah, while narrowing marginally by 1 point in Houston.
Overall, the balance between overvalued and undervalued ports showed no significant structural change during August, with Fujairah becoming the only overvalued port in the 380 HSFO segment. Undervaluation continued to prevail across the MDI, although individual hubs and fuel segments showed mixed dynamics. We expect this irregular pattern, with bunker fuel underpricing remaining predominant, to persist in September amid the ongoing conflict in the Middle East and elevated market uncertainty.
More detailed information on the correlation between market bunker prices and the MABUX Digital Bunker Benchmark is available in the “Digital Bunker Prices” section of mabux.com.
Other Global Bunkering Trends
• E-fuels: Europe currently has 69 maritime e-fuel projects, but only six are operational, according to T&E. China has just three operational projects, yet their combined output is already around 10 times higher, raising competitive pressure on Europe’s emerging e-fuel industry.
• EU shipping emissions: GHG emissions from EU-linked shipping rose 2.1% year-on-year to 156 million mtCO₂e in 2025. CO₂ emissions increased by 1.8%, while methane emissions surged by around 30%. The number of reporting vessels expanded to 17,000 following broader EU MRV requirements.
• ARA fuel oil stocks: ARA fuel oil inventories recovered by around 17% from May lows by mid-August but remained 34% below February levels. August imports more than doubled versus July, although prompt bunker availability remained tight, with recommended lead times of 5–7 days.
• China bunker quality: Marine insurer Gard reported that sulfur-related bunker claims more than tripled year-on-year in H1 2026 amid tighter enforcement of marine fuel regulations in China. Increased inspections, particularly across major Bohai Sea ports, are adding pressure on bunker suppliers and operators.
• Methanol bunkering: ISO released ISO 22120:2026, setting requirements for methanol bunkering transfer systems and equipment. The standard covers operational procedures, risk assessment, safety measures and personnel training, supporting further development of methanol as a marine fuel.
The global bunker market is expected to remain volatile in September, with Middle East developments and the Strait of Hormuz remaining the key drivers. Gradual recovery in Gulf oil flows may ease the geopolitical premium and pressure bunker prices, while tight distillate supply, low inventories and regional supply imbalances should limit the downside. Overall, MABUX expects the market to move toward gradual stabilization, but with irregular price fluctuations and significant upside risks in case of renewed geopolitical escalation.
By Sergey Ivanov, Director, MABUX